RBA Considers Further Rate Hikes Amid Falling House Prices
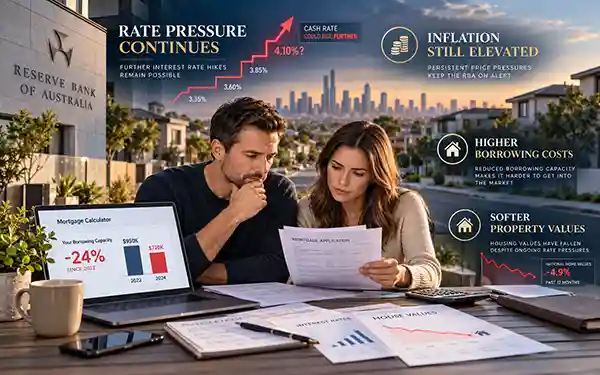
The Reserve Bank of Australia has made it clear that further interest rate increases remain possible if inflation does not return sustainably toward target, reinforcing expectations that borrowers may need to prepare for higher financing costs for longer.
Minutes from the RBA’s 28–29 September 2026 meeting show that the Board unanimously increased the cash rate by 25 basis points to 4.60%. Members noted that several upside risks to inflation had materialised, including stronger domestic cost pressures, higher global energy prices and resilient demand.
Importantly, the Board also stated that it would continue to do what it considers necessary to restore price stability, including raising the cash rate further if required. This means the September increase should not automatically be viewed as the end of the tightening cycle.
The latest inflation figures help explain the RBA’s caution. Australian Bureau of Statistics data show that annual CPI inflation increased to 4.0% in August 2026, up from 3.5% in July, while trimmed mean inflation remained at 3.6%.
At the same time, Australia’s housing market has already been adjusting to tighter financial conditions. National dwelling values have fallen materially from their earlier 2026 peak, with softer buyer demand, lower borrowing capacity and higher mortgage repayments contributing to weaker market conditions.
For Melbourne’s western growth corridor, the possibility of further rate increases is particularly important for first-home buyers and families relying on larger mortgages. Each additional increase in borrowing costs can reduce purchasing capacity and narrow the range of properties buyers can afford.
This can place further pressure on property values, particularly where sellers are competing for a smaller pool of finance-approved buyers. Homes that are priced realistically may continue to attract demand, while properties priced according to earlier market peaks could take longer to sell.
For existing homeowners, sustained higher interest rates mean mortgage repayments are likely to remain a major household expense. Borrowers approaching the end of fixed-rate periods or refinancing loans may need to reassess budgets and maintain larger financial buffers.
Investors face similar challenges. Higher interest expenses can reduce net rental returns, particularly where properties carry high levels of debt. Investors in Melbourne’s west may increasingly focus on properties with stronger yields, reliable tenant demand and lower holding costs rather than relying predominantly on short-term capital growth.
Rental conditions could also be affected. Some landlords may attempt to recover part of their higher financing costs through rent increases when leases are reviewed, although actual rental growth will continue to depend on local supply, vacancy rates and what tenants can afford.
For prospective buyers, weaker property prices may initially appear positive, but affordability is determined by both the purchase price and the cost of finance. A cheaper home does not necessarily become more affordable if interest rates rise enough to offset the reduction in price.
The RBA’s current stance therefore creates a challenging balance for the property market. Buyers may gain greater negotiating power as values soften, but borrowing remains expensive. Sellers may need to adjust price expectations, while investors must place greater emphasis on cash flow and sustainable debt levels.
For Melbourne’s western growth corridor, areas with strong population growth, transport links, employment access and rental demand may continue to attract interest despite the broader slowdown. However, the market is likely to become increasingly selective.
Overall, the latest RBA minutes reinforce the need for buyers, homeowners and investors to plan for the possibility that interest rates remain elevated for an extended period. Careful budgeting, realistic borrowing assumptions and strong financial buffers will remain important while inflation stays above target and monetary policy remains restrictive.
Summarised by Ravs Realtors from reporting by Domain.